India’s Solar Panel Factories Are Shutting Down – Here’s What’s Really Happening
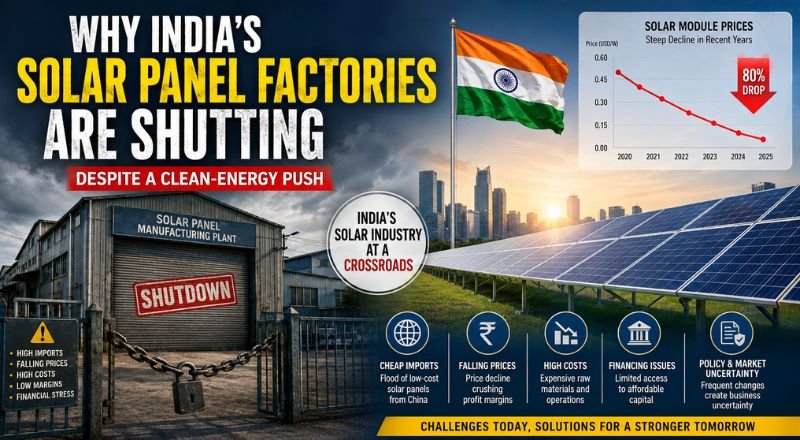
India’s solar energy sector is at a critical crossroads. While the country continues to install record levels of solar power—adding a record 44.61 GW in FY2025-26 alone —a wave of factory shutdowns among domestic solar panel manufacturers threatens to derail the nation’s clean energy ambitions . By late July 2026, close to one-third of India’s small and medium solar panel makers had halted production, putting approximately $4 billion in investment at risk .
This is not a story of falling demand, but of a severe supply chain bottleneck triggered by a government policy designed to achieve the opposite: reducing India’s reliance on Chinese imports.
The Policy That Backfired
On June 1, 2026, a new mandate took effect requiring solar projects to use only domestically produced solar cells, under the ALMM (Approved List of Models and Manufacturers) framework . The goal was to boost local manufacturing and strengthen India’s position in the global solar supply chain under the “Make in India” initiative.
But the policy immediately exposed a fundamental structural mismatch in India’s solar industry:
| Segment | Capacity | Notes |
|---|---|---|
| Module Assembly Capacity | ~200 GW | The ability to assemble finished solar panels |
| Cell Manufacturing Capacity | ~27 GW (cumulative), ~13.1 GW (effective) | The ability to make the cells that go inside panels |
| Annual Demand-Supply Gap | ~2.6 GW | The shortfall between domestic cell production and module assembly needs |
Before the policy took effect, over 90% of the cells used by Indian module makers came from China . Now, with those imports suddenly banned, manufacturers lacking their own cell production lines find themselves competing directly with large integrated players for a scarce domestic resource . Domestic cells cost almost double those made in China, and the waiting period stretches to six to eight months.
Real-World Impact
The numbers tell the story. According to industry sources:
- Nearly one-third of India’s small and medium solar module makers have already halted production since June 1, 2026 .
- These firms account for approximately 60% of India’s module manufacturing capacity .
- One manufacturer, Shailendra Shukla, chairman of Icon Solar, expects his production to shrink from 3.2 GW to just 1 GW .
- Capacity utilisation at module manufacturing plants has reportedly fallen to around 40%, raising concerns about oversupply and margin pressure .
Solar cell capacity is heavily concentrated. Gujarat alone accounts for 52.7% of India’s effective enlisted solar cell capacity (6,926 MW) , with the rest distributed across Tamil Nadu (2,556 MW), Telangana (1,450 MW), Karnataka (1,030 MW), and other smaller producing states . This geographical concentration means the supply shortage hits manufacturers outside Gujarat particularly hard.
Industry analysts have called the government’s expectation that new cell capacity could come online quickly unrealistic—estimating it will take three to five years to close the cell supply deficit .
Read Also: Tamil Nadu’s Solar Breakthrough Shows How India Can Lead the Global Clean Energy Transition
The China Factor
India’s push to decouple from China’s industrial ecosystem has faced a sobering reality check. The country still relies on China for 95% of its solar cell imports .
Adding to the problem, China has reportedly curbed exports of solar manufacturing technology, equipment, and technical support to India, making it even harder to scale up local cell production quickly . India’s upstream polysilicon and silicon wafer capacity remains nascent and heavily dependent on Chinese imports .
Large vertically integrated groups—including Adani, Waaree, Tata Power, Reliance, and Premier Energies—benefit from the Production Linked Incentive (PLI) program and control most of the access to locally made cells . Small and medium assemblers, who represent 60% of the solar module sector, remain exposed to the shortage, lacking priority access to this resource.
Broader Consequences
The shutdowns are not just an industry problem—they threaten India’s entire clean energy roadmap. The government has set a target of 500 GW of non-fossil fuel capacity by 2030, with solar expected to contribute more than 292 GW of that total, up from 162 GW currently .
But the cell shortage is already delaying projects and raising costs. Solar project capital expenditure could rise by about 35% until domestic cell supply scales up . If solar deployment slows, growing electricity demand will likely be met through greater use of coal, delaying the country’s transition to cleaner energy.
The Human Cost
Beyond the policy and trade dynamics, thousands of jobs are at stake. In Gujarat alone—India’s solar manufacturing hub—an estimated 45,000 jobs are tied to standalone module makers that lack their own cell production. Across the country, that figure rises to about 75,000 direct jobs.
The challenge is compounded by broader market trends. India’s module manufacturing capacity expanded to around 210 GW by the end of 2025, far exceeding estimated annual domestic demand of 40-45 GW . This structural oversupply—combined with technology transitions from MonoPERC to TOPCon modules—could push the industry into a phase of consolidation and further job losses .
Read Also:Electricity Costs Keep Rising — Solar Is the 2026 Solution
What Happens Next?
The government has extended the domestic-cell deadline to December 2026 for some projects in response to industry pressure . But industry groups say the waiver only offers limited relief unless it is widened to cover the entire sector.
For India’s solar ambitions, the choice is becoming clear: either bridge the cell manufacturing gap through investment and technology partnerships, or accept that a policy designed to build self-reliance has, at least in the short term, achieved the opposite.
Author: Solar Facts India Team
This article draws on official government data, industry association reports, and verified news sources to provide an independent analysis of India’s solar manufacturing sector. For more information, visit our About page or contact us at sonalkhanavi90@gmail.com.
Disclaimer: This content is for informational purposes only and does not constitute financial or investment advice. Readers should consult qualified professionals for decisions regarding solar investments. For our full disclaimer, please visit our Disclaimer page.
Related Posts
1 thought on “Why India’s Solar Industry Is Facing Factory Shutdowns in 2026”